Page: 1
/ 14
Total 163 questions
AICPA CPA Financial Accounting and Reporting CPA-Financial CPA Exam Questions
Question 1
In general, an enterprise preparing interim financial statements should:
Answer : D
Choice 'd' is correct. Generally accepted accounting principles that were used in the most recent annual report of an enterprise should be applied to interim financial statements of the current year, unless a change in accounting principle is adopted in the current year.
Choices 'a', 'b', and 'c' are incorrect, per above.
Question 2
According to the FASB conceptual framework, the process of reporting an item in the financial statements of an entity is:
Answer : D
Choice 'd' is correct. Recognition is the process of recording an item in the financial statements of an entity. SFAC 5 para. 6
Choice 'a' is incorrect. Allocation is the accounting process of assigning or distributing an amount according to a plan or a formulA. SFAC 6 para. 142
Choice 'b' is incorrect. Matching of costs and revenues is simultaneous or combined recognition of the revenues and expenses that result directly and jointly from the same transactions or other events. SFAC 6 para. 146
Choice 'c' is incorrect. Realization is the process of converting noncash resources and rights into money. SFAC 6 para. 143
Question 3
APB Opinion No. 28, Interim Financial Reporting, concluded that interim financial reporting should be viewed primarily in which of the following ways?
Answer : C
Choice 'c' is correct. Interim financial reporting should be viewed as reporting for an integral part of an annual period.
Choices 'a', 'b', and 'd' are incorrect, per the above rule.
Question 4
How should the effect of a change in accounting principle that is inseparable from the effect of a change in accounting estimate be reported?
Answer : A
Choice 'a' is correct. When the effect of a change in accounting principle is inseparable from the effect of a change in accounting estimate, the reporting treatment for the overall effect is as a change in estimate.
Thus, the effect is reported prospectively as a component of income from continuing operations. Under SFAS No. 154, this type of change is now called a change in accounting estimate affected by a change in accounting principle.
Choice 'b' is incorrect. Restatement of all prior periods is the retroactive accounting treatment that is applied to the correction of an error and the retrospective accounting treatment given to changes in accounting principle. However, a change in accounting principle that is inseparable from the effect of a change in accounting estimate is now treated as a change in accounting estimate.
Choice 'c' is incorrect. Correction of an error is given retroactive treatment as a prior period adjustment to retained earnings with restatement of prior periods. This is not the treatment appropriate for the effect of a change in accounting principle that is inseparable from the effect of a change in accounting estimate.
Choice 'd' is incorrect. While footnote disclosure is always appropriate for an accounting change, such disclosure alone is never the appropriate accounting treatment.
Question 5
During 1994, Orca Corp. decided to change from the FIFO method of inventory valuation to the weightedaverage method. Inventory balances under each method were as follows:
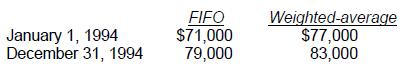
Orca's income tax rate is 30%.
Orca should report the cumulative effect of this accounting change as a(n):
Answer : A
Choice 'a' is correct. The cumulative effect of a change in accounting principle is shown as an adjustment to beginning retained earnings.
Choice 'b' is incorrect. The cumulative effect of a change in accounting principle is now presented as a separate category on the retained earnings statement and is not a component of net income.
Choice 'c' is incorrect. Extraordinary items are unusual and infrequent in nature. Extraordinary items have nothing to do with changes in accounting principle.
Choice 'd' is incorrect. A change in accounting principle affects retained earnings, not the income statement, under SFAS No. 154.
Question 6
On January 2, 1989, Union Co. purchased a machine for $264,000 and depreciated it by the straight-line method using an estimated useful life of eight years with no salvage value. On January 2, 1992, Union determined that the machine had a useful life of six years from the date of acquisition and will have a salvage value of $24,000. An accounting change was made in 1992 to reflect the additional data. The accumulated depreciation for this machine should have a balance at December 31, 1992, of:
Answer : D
Choice 'd' is correct, $146,000 accumulated depreciation balance at DeC. 31, 1992.

Question 7
During the first quarter of the calendar year, Worth Co. had income before taxes of $100,000, and its effective income tax rate was 15%. Worth's effective annual income tax rate for the previous year was 30%. Worth expects that its effective annual income tax rate for the current year will be 25%. The statutory tax rate for the current year is 35%. In its first quarter interim income statement, what amount of income tax expense should Worth report?
Answer : B
Choice 'b' is correct. When preparing interim financial statements, income tax expense is estimated each quarter using the effective tax rate expected to apply to the entire year.
Choice 'a' is incorrect. Worth should use the effective annual tax rate, not the effective tax rate for the quarter only.
Choice 'c' is incorrect. Worth should use the effective annual tax rate expected to apply to the current year, not the prior year's effective tax rate.
Choice 'd' is incorrect. Worth should use the effective annual tax rate, not the statutory tax rate.
Segment Reporting
 All Official Question Types