Page: 1
/ 14
Total 162 questions
APA Fundamental Payroll Certification FPC-Remote Exam Questions
Question 1
All of the following activities are examples of an internal control EXCEPT:
Answer : A
Comprehensive and Detailed Explanation:
Internal controls are processes used to ensure accuracy, security, and compliance in payroll operations. Effective internal controls include:
Option B (Segregating job duties) Prevents fraud by ensuring no one person has full control over payroll.
Option C (Rotating job duties) Reduces fraud risk and enhances cross-training.
Option D (Restricting system access) Protects sensitive payroll data.
Option A (Storing backup files on-site) is incorrect because internal control best practices recommend off-site or cloud backups to protect against data loss from disasters.
Payroll.org -- Payroll Internal Control Procedures
IRS -- Best Practices for Payroll Security
Question 2
Which of the following simulations would NOT be performed when testing a disaster recovery plan?
Answer : B
Comprehensive and Detailed Explanation:
A disaster recovery plan (DRP) ensures payroll continuity during emergencies. Key tests include:
Option A (Direct deposit & check printing) is correct because payroll must still be processed during a disaster.
Option C (Access to online payroll data) is necessary to ensure payroll can be processed remotely.
Option D (Network connectivity verification) is vital to confirm off-site payroll access.
Option B (Validating new hire record counts) is incorrect because it is a routine HR function, not part of disaster recovery. DRPs focus on ensuring payroll continues for existing employees rather than hiring functions.
Payroll.org -- Payroll Disaster Recovery Planning
IRS -- Business Continuity Guidelines for Payroll Processing
Question 3
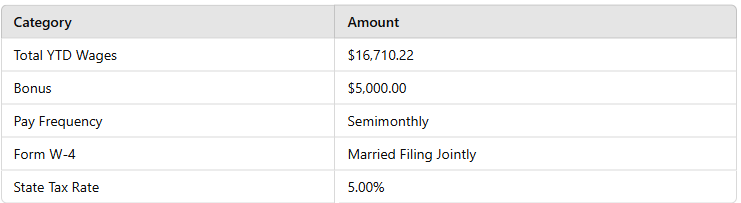
An exempt employee is being paid an annual discretionary bonus. The employee has submitted a 2020 W-4. Calculate the net pay based on the following information:
Answer : B
Comprehensive and Detailed Explanation:
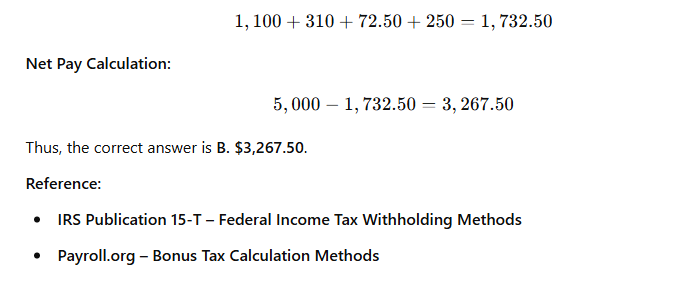
Using the IRS Supplemental Wage Method, the flat tax rate of 22% applies to bonuses:
Federal Income Tax:
$5,000 22% = $1,100.00
Social Security Tax:
$5,000 6.2% = $310.00
Medicare Tax:
$5,000 1.45% = $72.50
State Income Tax:
$5,000 5.0% = $250.00
Total Taxes Withheld:
Question 4
Payroll liability tax accounts should be reconciled at LEAST once a:
Answer : B
Comprehensive and Detailed Explanation:
Payroll liabilities (taxes, deductions, and withholdings) must be reconciled regularly to prevent errors and ensure compliance.
Best practice is monthly reconciliation (Option B) to ensure:
Payroll taxes match general ledger accounts.
Deposits are made on time to avoid IRS penalties.
Payroll liability accounts are balanced before quarterly tax filings.
Option A (Weekly) is impractical unless payroll runs very frequently.
Option C (Quarterly) and Option D (Yearly) are too infrequent and may result in tax errors or compliance issues.
Payroll.org -- Payroll Tax Liability Reconciliation Best Practices
IRS -- Payroll Tax Deposit and Reporting Compliance
Question 5
Which of the following statements about payments made under workers' compensation benefits is FALSE?
Answer : C
Comprehensive and Detailed Explanation:
Workers' compensation benefits are NOT subject to FUTA (Federal Unemployment Tax Act) as long as they are paid under a workers' compensation law.
Option A (Not included in gross income) is correct because workers' compensation is tax-exempt under IRS rules.
Option B (Received for work-related injuries/illnesses) is correct because these payments replace lost wages due to job-related incidents.
Option D (Not subject to FICA under state laws) is correct because workers' compensation payments are exempt from Social Security & Medicare taxes if they are made under a state-approved program.
Option C is incorrect because workers' compensation payments are NOT subject to FUTA, regardless of the amount paid.
IRS Publication 525 -- Taxability of Workers' Compensation
Payroll.org -- Payroll Taxation of Disability and Workers' Compensation Benefits
Question 6
On June 1st, the Payroll Department received an SUI rate change notice indicating a new rate effective January 1st of the current year. The system was not updated with the new rate until October 1st. SUI contribution recalculation will need to be done for:
Answer : D
SUI (State Unemployment Insurance) rate changes are often retroactive to January 1st.
Since the system was not updated until October, payroll must recalculate all affected quarters (1st, 2nd, and 3rd).
SUI Tax Compliance Guide (Payroll.org)
IRS Publication 15 (Employer's Tax Guide)
Question 7
Payroll staff should be aware of all of the following potential warning signs of a data breach EXCEPT:
Answer : C
Comprehensive and Detailed Explanation:
Payroll security professionals must monitor for potential payroll fraud or data breaches.
A (Excessive security reset requests) Could indicate a hacker attempting unauthorized access.
B (Large payroll data requests) Could signal attempted data theft.
D (Activity outside normal hours) Could be an external breach or insider threat.
Option C (Reprinting a W-2) is NOT necessarily suspicious, as employees frequently request reprints during tax season.
Payroll.org -- Payroll Data Security Best Practices
IRS -- Data Breach Prevention in Payroll
 All Official Question Types