Page: 1
/ 14
Total 185 questions
CSI Canadian Securities Course Exam 2 CSC2 Exam Questions
Question 1
What is the difference between sinking funds and purchase funds concerning the redemption of bonds poor to maturity?
Answer : A
Sinking funds require the issuer to redeem a specified portion of the bond issue at regular intervals. This ensures systematic debt reduction and is mandated regardless of market conditions.
Purchase funds, however, allow the issuer to buy back bonds only if they are available in the market at or below a stipulated price, making redemption conditional on market conditions.
Why Other Options are Incorrect:
B . Sinking funds can redeem bonds only if they trade below a stipulated price: This applies to purchase funds, not sinking funds.
C . Sinking funds involve the issuer determining when bonds are redeemed while purchase funds involve the investor determining when the bonds are redeemed: Investors have no role in determining bond redemption under either method.
D . Sinking funds can redeem the bonds any time while purchase funds follow a prearranged schedule: Sinking funds follow a schedule, and purchase funds rely on market conditions.
Reference: CSC Volume 1, Chapter 6, 'Bond Features -- Sinking Funds and Purchase Funds' explains these mechanisms for bond redemption.
Question 2
An analyst compiles the following information for Theta Inc.
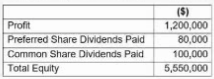
Based on the financial information provided, what will the dividend payout ratio be for Theta Inc.?
Answer : C
Question 3
What is the key objective for investors in alternative strategy funds?
Answer : C
Alternative strategy funds aim to achieve absolute returns, focusing on positive returns under various market conditions rather than comparing performance to a benchmark index. These strategies often include hedge funds and alternative mutual funds, using techniques like leverage, short selling, and derivatives to manage risk and enhance returns. The goal is not necessarily to outperform an index (as in option A) or match inflation rates (option D) but to deliver consistent positive returns.
Reference
CSC Volume 2, Chapter 21: Alternative Investments: Strategies and Performance, p. 21-3 to 21-24.
Question 4
Which one is a unique feature of mutual funds or ETFs?
Answer : C
Question 5
For what type of company is the dividend discount model least applicable?
Answer : D
The dividend discount model (DDM) is based on the premise that a company's intrinsic value is the present value of all future dividends. This model works best when:
Dividends are stable or follow a predictable growth rate.
The company has an established dividend payout history.
Inapplicability to Fluctuating Dividend Patterns: A company with changing dividend payments and fluctuating growth rates lacks the consistency required for the DDM. The fluctuating nature introduces uncertainty, making it difficult to estimate future dividends accurately. This diminishes the model's reliability in valuing such companies.
Comparison with Other Options:
Option A: Changing dividend payments but a stable growth rate could still provide a predictable valuation framework using DDM.
Option B: Stable dividends and a stable growth rate align perfectly with DDM assumptions.
Option C: Stable dividends and fluctuating growth rates are more predictable than Option D.
Supporting Study Material Reference:
Volume 2, Chapter 13 (Fundamental Analysis): Explains the relevance of consistent dividend patterns in equity valuation, emphasizing
Question 6
Which will taxed at the taxpayer' marginal tax rate?
Answer : A
Dividends from foreign corporations are taxed at the taxpayer's marginal tax rate because they are treated as regular income in Canada. Unlike Canadian dividends, which may qualify for a dividend tax credit to reduce the effective tax rate, foreign dividends do not receive preferential tax treatment under Canadian tax law.
Marginal Tax Rate: The rate at which the taxpayer's last dollar of income is taxed. Since foreign dividends do not qualify for tax credits, they are taxed as ordinary income.
Double Taxation Relief: While foreign dividends are fully taxable in Canada, tax treaties between Canada and other countries may allow a foreign tax credit to offset taxes paid to the foreign jurisdiction. However, this does not alter their treatment under the marginal tax rate.
Other options provided in the question:
Dividends not eligible for the dividend tax credit (Option C) are usually taxed at a higher rate, but Canadian non-eligible dividends receive some preferential treatment, unlike foreign dividends.
Foreign property valuation (Options B and D) is relevant for reporting requirements under Canadian tax laws, such as the T1135 Foreign Income Verification Statement, but does not affect the taxation of foreign dividends.
CSC Volume 2, Chapter 24: 'Canadian Taxation,' details the treatment of foreign income, including dividends and foreign tax credits.
Question 7
Companies W, X, Y, and Z ail issue preferred shares and have experienced the following conditions
Over the last five years:
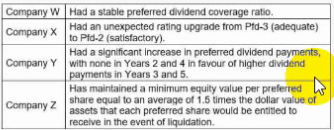
Based on the above, which company is most likely to experience an increase in the market price of its preferred shares?
Answer : D
 All Official Question Types