Page: 1
/ 14
Total 287 questions
PRMIA Exam I: Finance Theory, Financial Instruments, Financial Markets – 2015 Edition 8006 Exam Questions
Question 1
Theta for a call option:
Answer : C
Theta measures time decay, ie the change in value of the option with the passage of time. When the option is close to expiry, theta is very low as the value of the option is driven by intrinsic value rather than the time value. Therefore theta approaches zero as the option comes closer to expiry.
Question 2
Which of the following is true about the early exercise of an American call option:
Answer : B
Generally, it is not a good idea to exercise an option early as any more upside in the remaining period to expiry is being sacrificed. However, if an extraordinarily large dividend is coming due, and this dividend is larger than the interest foregone from holding the option, it may be a good idea to exercise the option early. In such cases, the exercise needs to happen before the ex-dividend date and not afterwards. Choice 'b' is therefore the correct answer.
Even if the option is deep in the money and delta is approaching 1, and exercise upon maturity is almost a certainty, it would still always be better to sell the option than exercise it . Therefore Choice 'a' is incorrect. Choice 'c' is correct in all cases except when a large dividend is coming in. Choice 'd' is not correct because an early exercise needs to happen prior to the ex-dividend date and not afterwards.
Question 3
A bank sells an interest rate swap to its client, with the client agreeing to pay the bank a fixed 4% and receive 3 month LIBOR + 100 basis points, payments due every quarter. After quarter 1, the 3 month LIBOR is 2% p
a. Which of the following payments will happen in respect of this swap, assuming the contract notional is $100m, and the rate convention is 30/360.
Answer : C
In an interest rate swap, only the net payment is made. In this case,
- the customer pays the bank 4%*(3/12)*$100m
- the bank owes the customer (2% + 100bp))*(3/12)*$100m
Therefore the customer pays (4% - (2% + 100bp))*(3/12)*$100m. 3/12 represents the 3 month time interval. This is equal to a net payment of $250k from the customer to the bank. Therefore Choice 'c' is the correct answer and the rest are incorrect.
Question 4
Determine the enterprise value of a firm whose expected operating free cash flows are $100 each year and are growing with GDP at 2.5%. Assume its weighted average cost of capital is 7.5% annually.
Answer : D
The operating free cash flows can be considered a perpetual annuity with a given growth rate.
The value of a perpetuity of a periodic cash flow of 'c', with a discount rate 'r' and growth rate 'g' is given by c/(r - g). In the given case, the company can be considered as providing a perpetual annuity which provides an annual cash flow of $100 which are growing at 2.5% (equal to the GDP's growth rate, as given), and whose cost of capital, or the discount rate to use, is 7.5%
Therefore the value of the firm in this case is given by $100/(7.5% - 2.5%) = $2,000. Recall that the value of the firm is equal to the Operating Free Cash Flow/Weighted Average Cost of Capital (OFCF/WACC). Therefore Choice 'd' is the correct answer.
Question 5
What is the approximate delta of an exactly at-the-money call option?
Answer : B
The delta of an at-the-money call option is close to 0.5. It is close to 1 when it is deep in the money. It is close to 0 when it is deep out of the money. It is never negative. Therefore Choice 'b' is the correct answer.
Question 6
The relationship between covariance and correlation for two assets x and y is expressed by which of the following equations (wherecovarx,yis the covariance betweenxandy,xandyare the respective standard deviations andx,yis the correlation betweenxandy):
A)
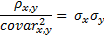
B)
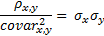
C)

D)
None of the above
Answer : B
Choice 'b' is the correct answer. The other relationships are not correct.
Question 7
Which of the following is an example of a multifactor model explaining expected asset returns:
1. Arbitrage pricing theory
II. Single index model
III. Capital asset pricing model
Answer : A
The arbitrage pricing theory is a multifactor model for explaining asset returns as it can be used to incorporate multiple factors, for example inflation, GDP growth rate, employment, interest rates etc to explain asset returns. Choice 'a' is the correct answer.
The single index model, as the name implies, uses only a single factor, and so does the CAPM which uses excess returns to explain an individual security's returns. Neither of these are multi-factor models.
 All Official Question Types