Page: 1
/ 14
Total 241 questions
PRMIA Operational Risk Manager (ORM) 8010 Exam Questions
Question 1
For a bank using the advanced measurement approach to measuring operational risk, which of the following brings the greatest 'model risk' to its estimates:
Answer : D
The greatest model risk when calculating operational risk capital comes from incorrect assumptions about correlations between different operational risks for which standalone risk calculations have been made. Generally, the correlation can be expected to be positive, and would therefore vary between 0 and 1. These two values determine the 'bounds' between which the total operational risk capital would lie, and these bounds are generally quite far apart. Therefore the total value of the operational risk capital is very sensitive to the value chosen for the correlation, and this is the source of the biggest model risk under the AMA.
Question 2
A portfolio has two loans, A and B, each worth $1m. The probability of default of loan A is 10% and that of loan B is 15%. The probability of both loans defaulting together is 1%. Calculate the expected loss on the portfolio.
Answer : B
The easiest way to answer this question is to ignore the joint probability of default as that is irrelevant to expected losses. The joint probability of default impacts the volatility of the losses, but not the expected amount. One way to think about it is to think of asset portfolios, where diversification reduces risk (ie standard deviation) but the expected returns are nothing but the average of the expected returns in the portfolio. Just as the expected returns of the portfolio are not affected by the volatility or correlations (these affect standard deviation), in the same way the joint probability of default does not affect the expected losses. Therefore the expected losses for this portfolio are simply $1m x 10% + $1m x 15% = $250,000.
This can also be seen from the lens of a joint probability distribution as follows:
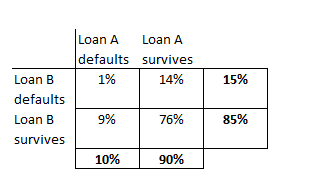
There are four possibilities for this portfolio:
- Only loan A defaults: loss of $1m: 9% probability
- Only loan B defaults: loss of $1m: 14% probability
- Both loan A and B default: loss of $2m: 1% probability
- Neither A nor B default: loss of $0m: 76% probability
Therefore the expected losses on the portfolio are ($1m x 9%) + ($1m x 14%) + ($2m x 1%) + ($0m x 76%) = $250,000.
(Notes: How is the above table calculated? The totals (10%, 90%, 15% and 85%) are filled in first. The top left cell (both A & B default) is given as 1%. We can now calculate the rest of the cells as the totals are known.)
Question 3
Which of the following credit risk models considers debt as including a put option on the firm's assets to assess credit risk?
Answer : C
The correct answer is Choice 'c'. The following is a brief description of the major approaches available to model credit risk, and the analysis that underlies them:
1. CreditMetrics: based on the credit migration framework. Considers the probability of migration to other credit ratings and the impact of such migrations on portfolio value.
2. CreditPortfolio View: similar to CreditMetrics, but adds the impact of the business cycle to the evaluation.
3. The contingent claims approach: uses option theory by considering a debt as a put option on the assets of the firm.
4. KMV's EDF (expected default frequency) based approach: relies on EDFs and distance to default as a measure of credit risk.
5. CreditRisk+: Also called the 'actuarial approach', considers default as a binary event that either happens or does not happen. This approach does not consider the loss of value from deterioration in credit quality (unless the deterioration implies default).
Question 4
Under the basic indicator approach to determining operational risk capital, operational risk capital is equal to:
Answer : A
Choice 'a' is the correct answer. According to the Basel II document, banks using the Basic Indicator Approach must hold capital for operational risk equal to the average over the previous three years of a fixed percentage (denoted alpha, and currently 15%) of positive annual gross income. Figures for any year in which annual gross income is negative or zero should be excluded from both the numerator and denominator when calculating the average.
Question 5
An error by a third party service provider results in a loss to a client that the bank has to make up. Such as loss would be categorized per Basel II operational risk categories as:
Answer : A
Choice 'a' is the correct answer. Refer to the detailed loss event type classification under Basel II (see Annex 9 of the accord). You should know the exact names of all loss event types, and examples of each.
Question 6
Under the KMV Moody's approach to calculating expecting default frequencies (EDF), firms' default on obligations is likely when:
Answer : D
An observed fact that the KMV approach relies upon is that firms do not default when their liabilities exceed assets, but when asset values are somewhere between short term liabilities and the total liabilities. In fact, the 'default point' in the KMV methodology is defined as the short term debt plus half of the long term debt. The difference between expected value of the assets in one year and this 'default point', when expressed in terms of standard deviation of the asset values, is called the 'distance-to-default'.
Therefore Choice 'd' is the correct answer. The other choices are incorrect.
Question 7
The loss severity distribution for operational risk loss events is generally modeled by which of the following distributions:
1. the lognormal distribution
2. The gamma density function
3. Generalized hyperbolic distributions
4. Lognormal mixtures
Answer : C
All of the distributions referred to in the question can be used to model the loss severity distribution for op risk. Therefore Choice 'c' is the correct answer.
 All Official Question Types